ATTENTION: HOMEOWNERS MANAGING MULTIPLE DEBTS
Keeping up with repayments, but struggling to build a buffer?
Explore whether consolidating your home loan, car finance, personal loans and credit cards could simplify your repayments and create room for emergency savings.
I'll walk you through the costs, loan term and trade-offs, so you can decide whether it makes sense for you.
See how I can help
Let's start with your situation
TESTIMONIALS
What clients say about working with us
For Homeowners Who Need Simpler Repayments And A Financial Buffer
Your debts and repayments reviewed
Options explained in plain English
Fees, loan terms and total costs compared
Cash flow and emergency savings considered
Step-by-step guidance
Support through settlement and ongoing reviews
STILL NOT SURE?
Frequently Asked Questions
Here's what we usually get asked
Could consolidating my debts lower my monthly repayments?
Yes - consolidation can lower your required monthly repayments, giving you more breathing room and the opportunity to build savings for what comes next. A longer loan term can increase total interest, so we’ll build a strategy around how you live, what matters to you and what you want to achieve.
Could I pay more interest overall?
Yes - a longer loan term can increase total interest, even with a lower rate. We’ll consider those costs and build a strategy that balances breathing room today with what you want to achieve over time.
Which debts can I consolidate into my home loan?
Credit cards, car loans and personal loans may be included. We’ll review your debts and assess whether bringing them together could make your repayments easier to manage.
Could this help me build an emergency buffer?
It could, if consolidation creates room in your budget. We’ll work towards a savings buffer that helps you feel more prepared for unexpected expenses, with a plan shaped around your income, commitments and priorities.
How much equity do I need?
It depends on your property’s value, mortgage balance and lender requirements. We’ll also review your income, expenses and credit history to assess which options may be available and affordable for you.
What fees will I pay?
We don’t charge a broker fee for total loan amounts of $400,000 or more. Below that, a fee may apply and will be quoted in writing for your agreement upfront. We’ll also explain any lender and third-party costs before you decide.
Will this affect my credit score?
Our initial conversation won’t affect your credit score. A formal loan application can. We’ll explain any credit checks before we proceed, so you know what’s involved at each step.
Is my home at risk?
Yes. If you secure debts against your home and cannot repay the loan, you could lose it. We’ll explain the risks and carefully assess whether the proposed repayments are sustainable for your household.
Do I need to change banks?
Not necessarily. We’ll consider your current lender and suitable alternatives. If your loan is fixed, we’ll factor in any break costs before recommending a change that suits your circumstances and plans.
What if I’ve missed payments or have credit issues?
You may still have options. We’ll take the time to understand what happened and where things stand today, without judgement. What’s available will depend on your circumstances and the lender’s assessment.
How long does it take, and what documents will I need?
Timing varies by lender and circumstances. You’ll usually need ID, income evidence, loan statements and expense details. We’ll give you a clear checklist, an estimated timeframe and guidance through each step.
What happens on our call?
We’ll talk through your current repayments, your priorities and what you’d like to achieve. From there, we’ll outline the next steps towards a strategy that fits your life. There’s no obligation to apply for a loan.
How We Help You Get Ahead
Start with a call
We’ll talk through your current repayments, what’s putting pressure on your budget and what you’d like to change. It starts with understanding what matters to you.
Build your plan
We’ll walk you through suitable options, explain the costs and trade-offs, and build a strategy around how you live and what you want to achieve.
Move forward
If you choose to proceed, we’ll guide you through the application and settlement, with ongoing reviews to support you as your circumstances and goals change.
MEET THE FOUNDER
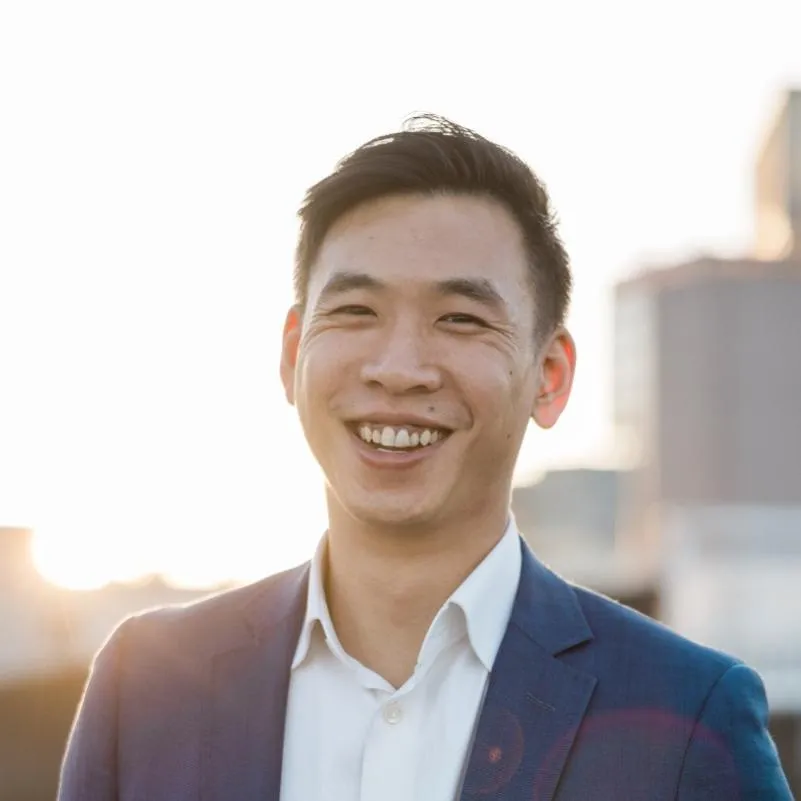
Hey, I'm Alex
I’m Alex Huynh, founder of KOI Financial Solutions. I believe good lending starts with understanding the person behind the repayments—what’s putting pressure on your budget, what matters to you and what you’d like life to look like.
At KOI, we take the time to understand that picture. We’ll explain your options clearly and build a strategy around how you live, whether your priority is more breathing room, savings for the unexpected or preparing for your next chapter.
You can expect thoughtful guidance through settlement and ongoing reviews, helping your lending keep pace as your life and priorities change.
10+ Years Lending Experience
Bachelor of Commerce in Finance & Business Strategy and Economic Management
Certificate IV in Finance and Mortgage Brokering
Diploma in Finance and Mortgage Brokering Management
Ready for more breathing room?
Let's build a lending strategy around how you live, what matters to you and what you want to achieve.
Answer a few questions to get started